When financial markets become unsettled, investors often seek protection in the Swiss franc. The currency benefits from Switzerland's institutional stability, credible monetary framework and long-established reputation for financial prudence.
These characteristics are valuable. They help preserve confidence when uncertainty rises elsewhere. Yet a currency regarded as safe by international investors can create difficult conditions for the country that issues it.
For Switzerland, this is not a theoretical concern. The strength of the franc has repeatedly complicated the relationship between monetary policy, export competitiveness and domestic economic activity.
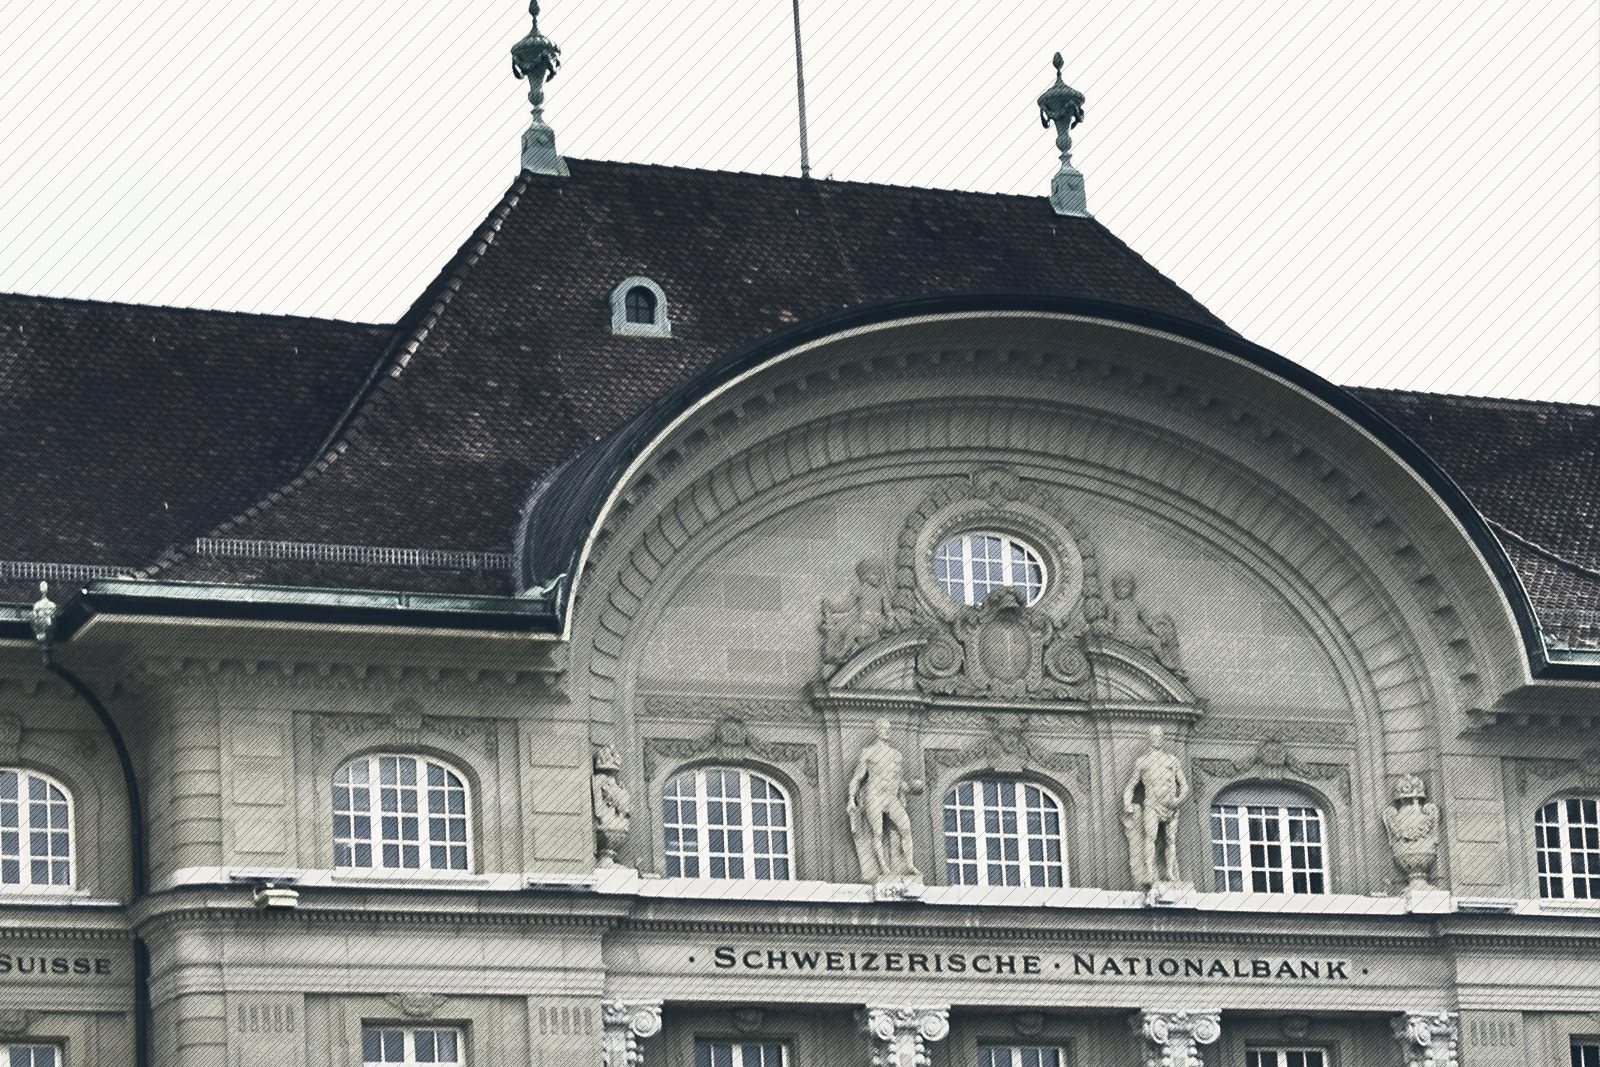
The latest decision by the Swiss National Bank (SNB) provides a useful occasion to examine that balance. On 24 September the SNB held its policy rate at zero per cent and reiterated its willingness to intervene in foreign exchange markets when necessary.
The decision reflected a relatively subdued domestic inflation environment, despite higher energy prices. Swiss annual inflation had risen from 0.6 per cent in May to 0.8 per cent in August. The central bank projected average inflation of 0.7 per cent for 2026, followed by 0.8 per cent in both 2027 and 2028.
Such figures suggest a degree of monetary stability that many advanced economies would welcome. But low inflation does not remove the challenges associated with currency movements.
A strong currency has two sides
For an investor holding Swiss franc assets, appreciation can provide additional returns when measured in another currency. For a Swiss exporter selling products abroad, the same movement may reduce competitiveness.
A company receiving revenue in euros or dollars but paying much of its wages and operating costs in francs faces a squeeze when foreign earnings convert into fewer units of domestic currency. The consequences depend on the company's pricing power, currency hedges and cost structure.
Manufacturers of specialised products may be able to maintain prices because customers have limited alternatives. Businesses competing primarily on cost have less flexibility. Tourism and certain domestic services can also become relatively more expensive for foreign visitors when the franc strengthens.
At the same time, a stronger currency can lower the domestic cost of imported goods, helping contain inflation. These competing effects explain why currency appreciation cannot be judged solely as a sign of national economic strength.
Its value depends on who is bearing the cost.
The central bank's narrow room for manoeuvre
The SNB operates in an environment that differs significantly from that of many other central banks. Switzerland has comparatively low inflation, a highly developed financial system and a currency that attracts international demand during periods of uncertainty.
If the franc appreciates sharply, imported disinflation can become an additional complication for monetary policy. Yet reducing interest rates to weaken the currency is not without cost.
With the policy rate already at zero, the scope for conventional easing is limited. Negative interest rates remain a possible instrument, but they bring consequences for financial institutions, savers and the wider allocation of capital.
Foreign exchange intervention offers another tool, although it raises questions about the size, composition and risk of central bank assets. The SNB's willingness to remain active in currency markets therefore reflects a practical necessity rather than an attempt to guarantee a particular exchange rate.
Monetary authorities can influence financial conditions. They cannot permanently insulate a small, open economy from global capital movements.
What wealth preservation actually requires
For internationally diversified investors, the franc remains an important component of currency risk management. But owning a stable currency and constructing a resilient portfolio are separate exercises.
A portfolio concentrated heavily in Swiss franc cash may preserve purchasing power under certain circumstances while sacrificing returns available elsewhere. An investor with substantial future liabilities in euros or dollars may also face a mismatch if assets and obligations are denominated in different currencies.
The relevant question is not which currency has the strongest reputation. It is which combination of assets and currencies best matches the investor's future financial needs.
That requires consideration of liquidity, investment horizon, valuation and exposure to unexpected movements in exchange rates. Currency diversification should serve a defined purpose. It should not become an emotional response to market volatility.
The distinction is particularly important when investors purchase an asset after a prolonged period of appreciation. A reputation for safety does not guarantee an attractive entry price.
Stability is an advantage to preserve
Switzerland's economic resilience rests on more than the franc. It depends on productive companies, reliable institutions, skilled labour and a financial system capable of serving domestic and international economic activity.
Currency stability supports those advantages. Excessive or unpredictable appreciation can complicate them. The appropriate policy objective is therefore not to maximise the franc's strength.
It is to maintain monetary stability while allowing the economy to remain competitive. For investors, a similar principle applies.
A defensive asset is useful when it reduces an identified risk without creating disproportionate exposure elsewhere. The Swiss franc deserves its place among the world's established reserve and safe-haven currencies.
But no currency should be treated as a substitute for sound investment judgement. Safety is not the absence of price movements. Nor is it simply the ability to withstand the next financial disturbance.
For long-term investors, genuine financial security comes from preserving the ability to meet obligations across a range of economic conditions. The franc can help achieve that objective.
It cannot achieve it alone.