Egypt has found a new way to reassure its creditors: sell them a piece of its history.
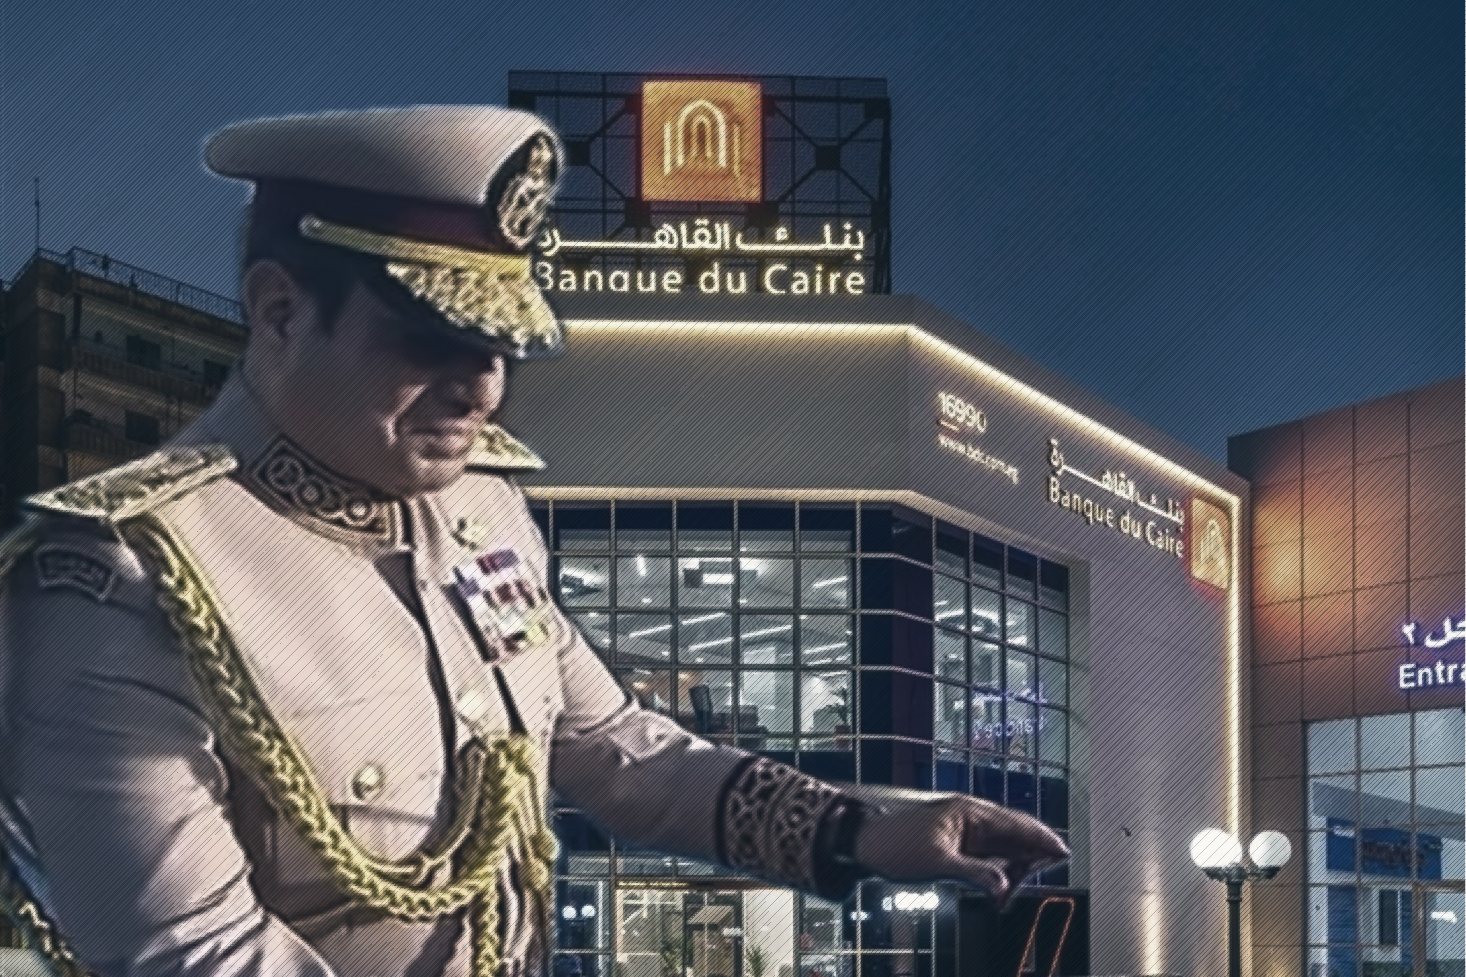
On 2 November the Egyptian government celebrated the stock-market debut of Banque du Caire, one of the country's oldest financial institutions. Founded in 1952, the bank has survived a revolution, nationalisation, wars, successive economic crises and a previous attempt to sell it. It has now surrendered 45 per cent of its equity to investors in an offering worth 36.37bn Egyptian pounds, about $658m, the largest listing by value in the history of the Egyptian Exchange.
The government hailed the transaction as a triumph for economic reform. Investors responded enthusiastically: the retail tranche was more than 27 times subscribed, and the shares rose by 6.3 per cent on their first day of trading. Mostafa Madbouly, the prime minister, presented it as evidence of renewed confidence in Egypt's economy.
But the more revealing announcement came afterwards. On 3 November EnterpriseAM, a business publication, reported, citing a senior government official, that the finance ministry would receive up to half the proceeds, about 18.2bn pounds, to ease pressure from public debt.
That is the uncomfortable reality behind the celebratory headlines: a state selling ownership of an established financial institution while struggling to contain the liabilities accumulated under its own economic policies.
The distinction matters. Privatisation can finance a country's future. It can also become an expensive way of paying for its past. Egypt increasingly risks confusing the two.
The bank Mubarak's government would not sell cheaply
The historical irony is difficult to ignore. Banque du Caire was founded in May 1952, before the Egyptian republic itself existed. It helped finance Egypt's cotton trade during the Suez crisis and was nationalised in 1961.
In 2008, under Hosni Mubarak, the government tried to sell 67 per cent of the bank. The process attracted international bidders, including National Bank of Greece, Mashreq of the United Arab Emirates and a consortium led by Arab Bank. The highest offer, from National Bank of Greece, was about $1.4bn for the controlling stake, valuing the whole bank at roughly $2bn. The government postponed the sale because the bid fell short of its minimum price of $1.6bn.
It would be historically dishonest to portray Mubarak as an opponent of privatisation. His government initiated the sale, and there is no evidence that he personally vetoed it. The documented reason was straightforward: the government refused the price.
Yet that makes today's contrast all the more striking. Eighteen years later, at its IPO price, the whole of Banque du Caire was valued at roughly $1.5bn.
The figures cannot be compared mechanically. Egypt's currency, banking system, asset valuations and economic conditions have changed profoundly since 2008. Nevertheless, the difference raises an important question about what has happened to the international value of Egyptian financial assets. A government once unwilling to accept a particular price for its bank is now celebrating a sale completed against a backdrop of exceptional fiscal pressure.
The lesson is not that all privatisation is wrong. It is that the financial desperation of a seller can matter as much as the quality of the asset being sold.
The debt is not the worst part. The interest is
Egypt's problem is no longer adequately described by the size of its public debt. It is the increasingly suffocating cost of carrying it.
The budget approved for the 2026-27 fiscal year allocates about 2.419trn pounds to interest payments. Not to repaying the original loans. Not to building factories, financing research or modernising public services. To paying the interest.
By comparison, the budget allocates about 553.7bn pounds to public investment. Interest payments are more than four times that amount. A further 2.808trn pounds is set aside to repay the principal on loans.
The IMF reported in March that interest payments were absorbing about 83 per cent of tax revenue, and that Egypt's reliance on short-term domestic borrowing exposed it to serious refinancing risks. Its review in August acknowledged improvements in growth, inflation and external buffers, but warned that high debt and large financing needs still left the economy vulnerable.
This is the fiscal predicament against which Banque du Caire has been sold. To be precise, the reported transfer of proceeds to the treasury is intended to ease debt pressures; the available evidence does not show that the money is earmarked specifically for interest.
That distinction does not absolve the government's broader strategy. When interest consumes such an extraordinary share of public resources, asset sales become part of an increasingly costly struggle to buy fiscal breathing space. A country that sells productive assets to relieve the pressure of unproductive liabilities has not necessarily solved its economic problem. It may merely have postponed the next instalment.
Reform, or the liquidation of accumulated wealth?
There is a legitimate economic argument for privatisation. Governments need not own every bank, factory, hotel or commercial enterprise. Private ownership can strengthen governance, sharpen competition, attract expertise and mobilise investment, and Egypt's banking sector has shown that privately controlled institutions can compete successfully.
The Banque du Caire offering also has genuine merits. It attracted international institutional investors, including the IFC and the EBRD, deepened the Egyptian Exchange and left Banque Misr with a majority holding of 55 per cent. It was not the wholesale disposal of the bank.
But the crucial question is not whether investors wanted the shares. It is what Egypt intends to do with the money. The transaction was a secondary offering: existing shares were sold by Banque Misr. It did not, by itself, inject fresh capital into Banque du Caire to finance more lending or expansion. Part of the proceeds is reportedly destined for the treasury instead.
That creates a fundamental policy test. Is Egypt converting state ownership into more productive private investment, or converting valuable public holdings into temporary fiscal relief? An oversubscribed IPO cannot settle the question. Nor should a sale be called structural reform merely because ownership changes hands. Genuine reform requires an economy in which businesses can compete fairly, public investment is rigorously assessed, government borrowing produces measurable returns and the state becomes less dependent on extracting value from existing assets.
The IMF itself identified a troubling inconsistency in March: while Egypt's divestment programme had largely stalled over the previous two years, new military-linked entities had been created. That raises an obvious question. Why should the state reduce its ownership of established commercial assets if it continues to expand its economic presence elsewhere?
Selling shares in a historic bank while leaving deeper questions about state competition, public procurement and politically directed investment unresolved is not a comprehensive economic transformation. It is, at best, a partial reform.
The accountability missing from the balance sheet
Egypt's fiscal difficulties cannot be analysed without examining the quality of the decisions that produced them. For years the government has pursued ambitious infrastructure programmes and capital-intensive developments while relying heavily on borrowing and state-directed investment. Some projects may generate lasting economic benefits. Others require far more convincing public evidence of their returns.
The IMF has previously highlighted the fiscal risks of large investments undertaken outside the ordinary budget, including the New Administrative Capital, and has called for greater transparency and oversight of public-sector operations.
The governance problem extends beyond fiscal accounting. In Transparency International's 2025 Corruption Perceptions Index, Egypt scored 30 out of 100, ranking 130th of 182 countries. The index records perceptions of public-sector corruption; it does not show that the Banque du Caire transaction is corrupt or that any official misappropriated money. But it reinforces the need for scrutiny in an economy where decisions about public assets carry consequences for generations.
The central issue is not whether every pound borrowed was stolen or wasted; such an accusation would require evidence. It is whether citizens have been given enough information to distinguish economically necessary investment from politically motivated spending, sound procurement from costly inefficiency, and legitimate public borrowing from decisions whose consequences are passed on to taxpayers.
When a government's borrowing produces enormous interest obligations, those responsible should face rigorous public accounting before the state begins disposing of assets accumulated over decades. Otherwise the risks of economic policy are socialised while the ownership of public wealth is progressively transferred. That is not a sustainable definition of reform.
A successful IPO is not a successful economy
The government has reasons to welcome the market's response. Foreign investment is valuable. Reducing public debt is necessary. A more competitive private sector is essential. And the government has made measurable progress in restoring elements of macroeconomic stability after repeated shocks.
Yet none of these achievements makes every asset sale economically wise. A well-managed privatisation programme should set transparent valuations, make a compelling economic case for each sale, disclose where the proceeds go and show how the transaction strengthens long-term productive capacity. Without those safeguards, privatisation risks becoming a fiscal habit rather than a development strategy.
The question Egyptians deserve to have answered is not simply how much Banque du Caire fetched. It is whether the sale will make the country less likely to need another such transaction in five years. If that cannot be demonstrated, the government's enthusiasm is premature.
An investor may reasonably celebrate buying a stake in an established bank. A treasury may welcome a temporary easing of financial pressure. But the public, which must live with the consequences of both the borrowing and the divestment, is entitled to a far higher standard of proof.
Egypt's economic future cannot be secured indefinitely by selling assets created in its past. A nation does not become wealthier merely because it finds buyers for what it already owns, and a government that repeatedly sells yesterday's achievements to finance today's obligations should not mistake the applause of investors for the verdict of history.
The shares have been sold. The creditors may receive some relief. The debt remains, and the next generation inherits less of the bank.